Business Finance
Mudra Loan Eligibility and How to Apply in India
Learn Mudra loan eligibility, Shishu, Kishor, Tarun and Tarun Plus limits, required documents and how to apply for business finance in India.
Starting a small business or expanding an existing one often requires additional funding. Whether you run a retail shop, a service business, a manufacturing unit or a small trading enterprise, access to finance can help you purchase equipment, manage working capital and support business growth.
The Pradhan Mantri MUDRA Yojana (PMMY) is a Government of India scheme designed to facilitate institutional credit for eligible micro-enterprises. It offers financing through participating banks and other lending institutions for qualifying income-generating business activities.
If you are searching for Mudra Loan Eligibility and How to Apply, this guide explains the loan categories, eligibility considerations, documents, application process and important points to check before applying. Business owners in Gwalior can also use this information to prepare for a discussion about their financing requirements with Pratham Finance.
What Is a Mudra Loan?
A Mudra loan is financing provided under the Pradhan Mantri MUDRA Yojana to eligible micro-enterprises. The scheme supports income-generating activities in manufacturing, trading and services, including certain activities allied to agriculture, such as dairy, poultry and beekeeping.
Depending on the applicant's requirements and the lender's assessment, financing may support working capital or eligible business investments.
Mudra loans are provided by participating lending institutions, including banks, non-banking financial companies (NBFCs) and microfinance institutions. MUDRA itself does not mean that every applicant automatically receives a loan; the lending institution evaluates the application under applicable rules. <Cite refs={["turn518237search0","turn518237search3"]}/>
Mudra Loan Categories and Loan Amounts
Under PMMY, loan categories are structured around the funding requirements and growth stage of the business.
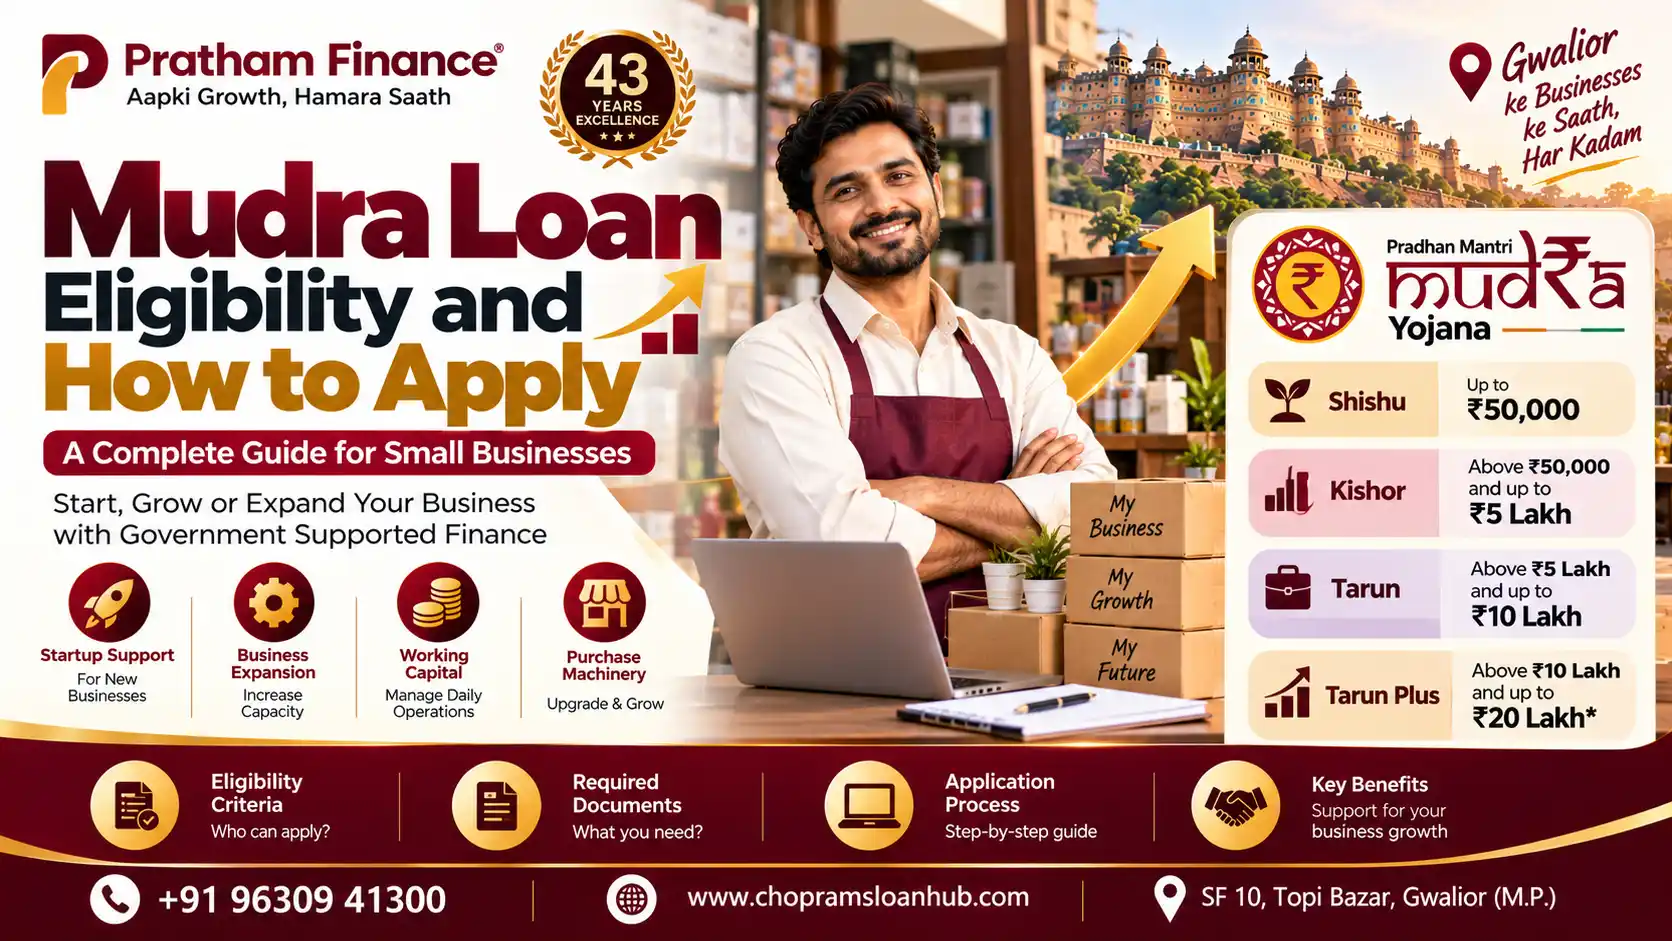
Loan categoryLoan amountShishuUp to ₹50,000KishorAbove ₹50,000 and up to ₹5 lakhTarunAbove ₹5 lakh and up to ₹10 lakhTarun PlusAbove ₹10 lakh and up to ₹20 lakh, subject to eligibility
Important: Tarun Plus is intended for entrepreneurs who have previously availed and successfully repaid a Tarun-category loan, in accordance with the scheme's applicable conditions. Applicants should confirm the current requirements with the participating lender. <Cite refs={["turn518237search0","turn518237search1"]}/>
Who Is Eligible for a Mudra Loan?
Mudra loan eligibility depends on the nature of the business, the applicant's financial position and the participating lender's assessment.
Applicants may include individuals and eligible business entities seeking finance for an income-generating micro-enterprise.
Common eligibility considerations include:
- Eligible business activity: The business should fall within the activities covered by PMMY.
- Business purpose: The funds should be intended for an eligible income-generating business activity.
- Business plan: Applicants should be able to explain their business model, funding requirement and how the funds will be used.
- Repayment capacity: The lender may assess expected income, cash flow and existing financial commitments.
- Credit history: Previous borrowing and repayment behaviour may be considered as part of the lender's assessment.
- Business documentation: Applicants must provide the information and documents required by the relevant lending institution.
- Scheme-specific conditions: Additional requirements may apply depending on the loan category and business circumstances.
Both new and existing eligible businesses may explore the scheme. However, eligibility does not guarantee approval, and the lender determines whether to sanction the loan.
What Can a Mudra Loan Be Used For?
Depending on the activity and lender's terms, Mudra financing may support a range of business requirements.
1. Starting a Small Business
Entrepreneurs planning an eligible income-generating venture may explore financing for initial business requirements, subject to the lender's assessment.
2. Purchasing Machinery and Equipment
Small manufacturers and service providers may need tools, machinery or equipment to begin operations or improve productivity.
3. Managing Working Capital
Eligible businesses may require funds for inventory, raw materials, supplier payments and other operational needs.
4. Expanding a Retail or Trading Business
Shopkeepers, wholesalers and traders may explore financing for eligible stock purchases or business development.
5. Supporting Service Businesses
Eligible service enterprises may need funds for equipment, business setup or other approved requirements.
6. Allied Agricultural Activities
Certain income-generating activities allied to agriculture, including dairy, poultry and beekeeping, may fall within the scheme's scope. Eligibility should be confirmed for the specific activity. <Cite refs={["turn518237search3","turn518237search15"]}/>
Documents Required for a Mudra Loan
The exact document checklist varies by lender, business type, loan amount and whether the application is for a new or existing enterprise.
Commonly requested documents may include:
Identity and address proof
- PAN card and other accepted identity documents
- Residential address proof
- Business address proof, where applicable
Business-related documents
- Business registration documents, where applicable
- GST registration, where applicable
- Udyam registration, where applicable
- Details of the proposed or existing business
Financial information
- Bank statements, where required
- Details of business income and expenses
- Existing loan information, where applicable
- Estimated project cost and funding requirement
Business plan or project details
- Description of the business activity
- Purpose of the loan
- Equipment quotations, where applicable
- Estimated revenue and operating expenses
- Expected repayment plan
Your lender may request additional documents during verification. Before submitting an application, obtain the latest checklist directly from the institution handling your loan.
How to Apply for a Mudra Loan
Follow these steps to prepare and submit your application.
Step 1: Identify Your Business Funding Requirement
Decide how much money your business needs and what the funds will be used for. Prepare an estimate covering equipment, inventory, working capital or other eligible expenses.
Step 2: Check the Appropriate Loan Category
Review the Shishu, Kishor, Tarun and Tarun Plus categories. If you are seeking a Tarun Plus loan, confirm that you meet its previous Tarun-loan repayment condition.
Step 3: Prepare Your Business Plan
Explain what your business does, how much funding is required and how the funds will generate income. For an existing business, include relevant information about operations and financial performance.
Step 4: Collect the Required Documents
Prepare identity documents, business details, financial records and other documents requested by the lender. Ensure that all information is accurate and consistent.
Step 5: Approach a Participating Lending Institution
You can contact a participating bank, NBFC or microfinance institution that offers PMMY loans. Ask about its application process, eligibility criteria, current interest rate, fees and repayment terms.
Step 6: Submit the Application
Complete the application form and submit the requested documents through the lender's accepted channel. Online application options may also be available for relevant credit schemes through official platforms.
Step 7: Complete Verification and Review the Offer
The lender may assess your business activity, financial information, credit profile and repayment capacity. If your application is approved, carefully review the sanctioned amount, interest rate, repayment schedule and applicable charges before accepting the offer.
Approval and disbursement timelines depend on the lender and the completeness of your application.
Is a Mudra Loan Collateral-Free?
PMMY is designed to facilitate collateral-free institutional credit for eligible micro-enterprises. However, applicants must still satisfy the applicable scheme conditions and the lender's assessment requirements.
Collateral-free does not mean documentation-free or guaranteed approval. The lender may require primary security over assets created or financed through the loan, along with other documents and undertakings under its applicable terms.
Always ask the participating institution to explain the security requirements for the particular product before proceeding. <Cite refs={["turn518237search0","turn518237search8"]}/>
What Is the Interest Rate on a Mudra Loan?
There is no single interest rate that applies to every Mudra loan. The applicable rate and repayment conditions depend on the participating lender, loan product and applicant's profile.
Before accepting an offer, ask for details about:
- Applicable interest rate and how it is calculated
- Loan tenure and monthly repayment amount
- Processing and documentation fees
- Any applicable taxes or other charges
- Conditions for early repayment or delayed payment
Compare the overall borrowing cost and make sure that the expected repayments are manageable for your business.
Mudra Loan for Small Businesses in Gwalior
Business owners in Gwalior may need finance for retail shops, trading activities, manufacturing units, service enterprises or eligible allied agricultural activities.
Before applying, prepare a clear estimate of your funding requirement and gather the documents relevant to your business. This can help you have a more productive discussion with the participating lender.
Pratham Finance, Gwalior, can be approached to discuss business funding needs and explore potentially suitable financing options. Confirm whether the specific Mudra loan product or application assistance you require is available before proceeding; do not assume that every finance provider directly sanctions PMMY loans.
Common Mistakes to Avoid When Applying
A well-prepared application can make the process easier to manage. Keep these points in mind:
- Applying under a loan category without checking its eligibility conditions.
- Providing an unclear business purpose or unrealistic financial projections.
- Submitting incomplete or inconsistent documents.
- Underestimating the business's monthly expenses and repayment obligations.
- Assuming that collateral-free financing means automatic approval.
- Ignoring processing fees, interest costs or repayment conditions.
- Relying on unofficial claims of guaranteed approval.
Take time to understand the lender's terms and borrow only what your business can reasonably repay.
Frequently Asked Questions About Mudra Loans
1. What is the maximum Mudra loan amount?
The scheme provides loans up to ₹20 lakh under Tarun Plus for eligible entrepreneurs who have previously availed and successfully repaid a Tarun-category loan. Other categories have lower limits, and the lender determines the amount sanctioned.
2. Can a new business apply for a Mudra loan?
Eligible entrepreneurs planning an income-generating micro-enterprise may explore PMMY financing. Approval depends on the business proposal, documentation, lender criteria and applicable scheme conditions.
3. Is a Mudra loan available without collateral?
PMMY is designed to support collateral-free institutional credit for eligible micro-enterprises. Applicants must still meet the lender's requirements and should confirm the security conditions of the specific loan.
4. Can I apply for a Mudra loan online?
Online application options may be available through participating lenders and relevant official platforms. Check the current application process on the institution's official website or contact its branch.
5. Can an existing business apply for a Mudra loan?
Eligible existing micro-enterprises may apply for financing for approved business requirements, subject to the relevant loan category, lender assessment and applicable conditions.
6. Does every applicant receive the requested loan amount?
No. The lender evaluates the application and decides whether to approve it and what amount, if any, to sanction. Approval and terms are not guaranteed.
Conclusion
The Pradhan Mantri MUDRA Yojana can be an option for eligible micro-enterprises seeking finance for business activities, equipment, working capital or growth. Understanding the loan categories, eligibility requirements and documentation process can help you prepare before approaching a lender.
If you are exploring business finance in Gwalior, begin by defining your funding requirement, preparing a realistic business plan and comparing the terms offered by participating institutions. Pratham Finance can be approached to discuss your broader business funding needs and explore potentially suitable financing options.
Disclaimer: This article is for general informational purposes only and is not a loan offer or a guarantee of eligibility or approval. Scheme conditions, lender requirements, interest rates, charges and application procedures may vary. Confirm the latest requirements with an authorised participating lending institution before applying.