Pratham Finance
How to Get a Collateral-Free Business Loan in India? A Complete Guide by Pratham Finance, Gwalior
Learn how to get a collateral-free business loan in India. Explore eligibility, documents, government schemes and business loan assistance by Pratham Finance in Gwalior.
Introduction: Need a Business Loan Without Pledging Property?
Do you want to expand your business but do not have property or other assets to offer as security? A collateral-free business loan may help you access funds for business expansion, working capital, purchasing machinery, increasing inventory or managing operational expenses.
For many small and medium-sized enterprises (MSMEs) in India, arranging funds can be challenging. Banks and financial institutions may ask for property, fixed deposits or other collateral for certain types of loans. However, eligible businesses may qualify for financing without pledging traditional collateral, depending on the lender's policies, credit assessment and applicable government-backed guarantee schemes.
If you are looking for business loan assistance in Gwalior, Pratham Finance can be your starting point for exploring suitable business financing options. The objective is to understand your funding requirements, assess available options and identify a loan structure that fits your business profile.
In this guide, you will learn how collateral-free business loans work, who may qualify, which documents are generally required, and how to improve your chances of approval.
Key Takeaways
- A collateral-free business loan generally does not require the borrower to pledge property or other specified assets as security.
- Approval depends on factors such as business turnover, credit history, repayment capacity, existing liabilities and lender policy.
- Banks, NBFCs and eligible government-backed credit guarantee programmes may offer different financing options.
- Udyam Registration, GST records, income-tax returns and bank statements can help demonstrate business activity and financial performance.
- A collateral-free loan is not automatically interest-free, fee-free or guaranteed to be approved.
- Businesses in Gwalior can approach Pratham Finance to explore suitable financing options, subject to eligibility and lender approval.
What Is a Collateral-Free Business Loan?
A collateral-free business loan is a type of business financing in which the borrower is not required to pledge specified assets, such as residential property, commercial property or machinery, as collateral for the loan.
Instead of relying primarily on pledged assets, the lender evaluates the business's financial position and ability to repay the borrowed amount.
Depending on the product, lenders may consider:
- Annual business turnover and profitability.
- Credit history and repayment behaviour.
- Current bank balance and cash flow.
- Business vintage and stability.
- Existing loans and monthly obligations.
- GST returns and income-tax returns, where applicable.
- Nature of the business and intended use of funds.
Important: Collateral-free does not mean risk-free. The borrower remains responsible for repaying the loan, and a lender may require a personal guarantee or other undertakings, depending on the product and applicable rules.
Example: How a Collateral-Free Loan Can Help
Suppose a manufacturing business in Gwalior receives additional orders but needs ₹15 lakh to purchase raw materials and increase production.
The business owner may not want to mortgage a family property to obtain funding. An eligible unsecured business loan or financing supported by an applicable credit guarantee arrangement could be worth exploring.
The lender would assess the business's cash flow, repayment capacity, credit profile and other relevant factors before making a decision. The amount, interest rate, tenure and approval would depend on the specific financing option.
This is an illustrative example, not a promise of loan approval or a quoted offer from any lender.
Types of Collateral-Free Business Loan Options in India
There is no single loan product suitable for every business. The right option depends on your funding requirement, business size, financial records and repayment capacity.
Loan optionSuitable purposeKey considerationUnsecured business loanExpansion, equipment, inventory or operating expensesDepends on lender eligibility and credit assessmentWorking capital financeManaging day-to-day business expensesLimits and repayment terms depend on cash-flow needs and the facilityMSME financingFunding eligible micro, small and medium enterprisesProduct terms vary by bank, NBFC and schemeGovernment-backed credit guarantee-supported loanEligible business financing supported by a qualifying guarantee programmeThe lender must meet scheme requirements; a guarantee is not automatic borrower approvalBusiness overdraft or cash creditManaging short-term cash-flow fluctuationsAvailability, security requirements and renewal terms varyMachinery or equipment financePurchasing eligible machinery or business equipmentThe financed equipment may itself serve as security
Before applying, ask whether the product is genuinely collateral-free, whether a guarantee is required, whether a personal guarantee applies, and what fees and repayment conditions will be charged.
Government Schemes That May Support Collateral-Free Business Finance
Eligible Indian businesses may be able to explore government-backed programmes designed to improve access to credit. Scheme conditions, limits and participating lenders must be checked against the latest official guidelines.
1. Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE)
CGTMSE operates a credit guarantee framework for eligible credit facilities extended by participating member lending institutions to qualifying micro and small enterprises.
The guarantee is provided to the lending institution under the scheme's applicable conditions. It is not a direct loan from CGTMSE to the business owner, and it does not mean that every applicant will receive a loan without security.
Ask the lender whether your business and proposed facility qualify under the current CGTMSE framework.
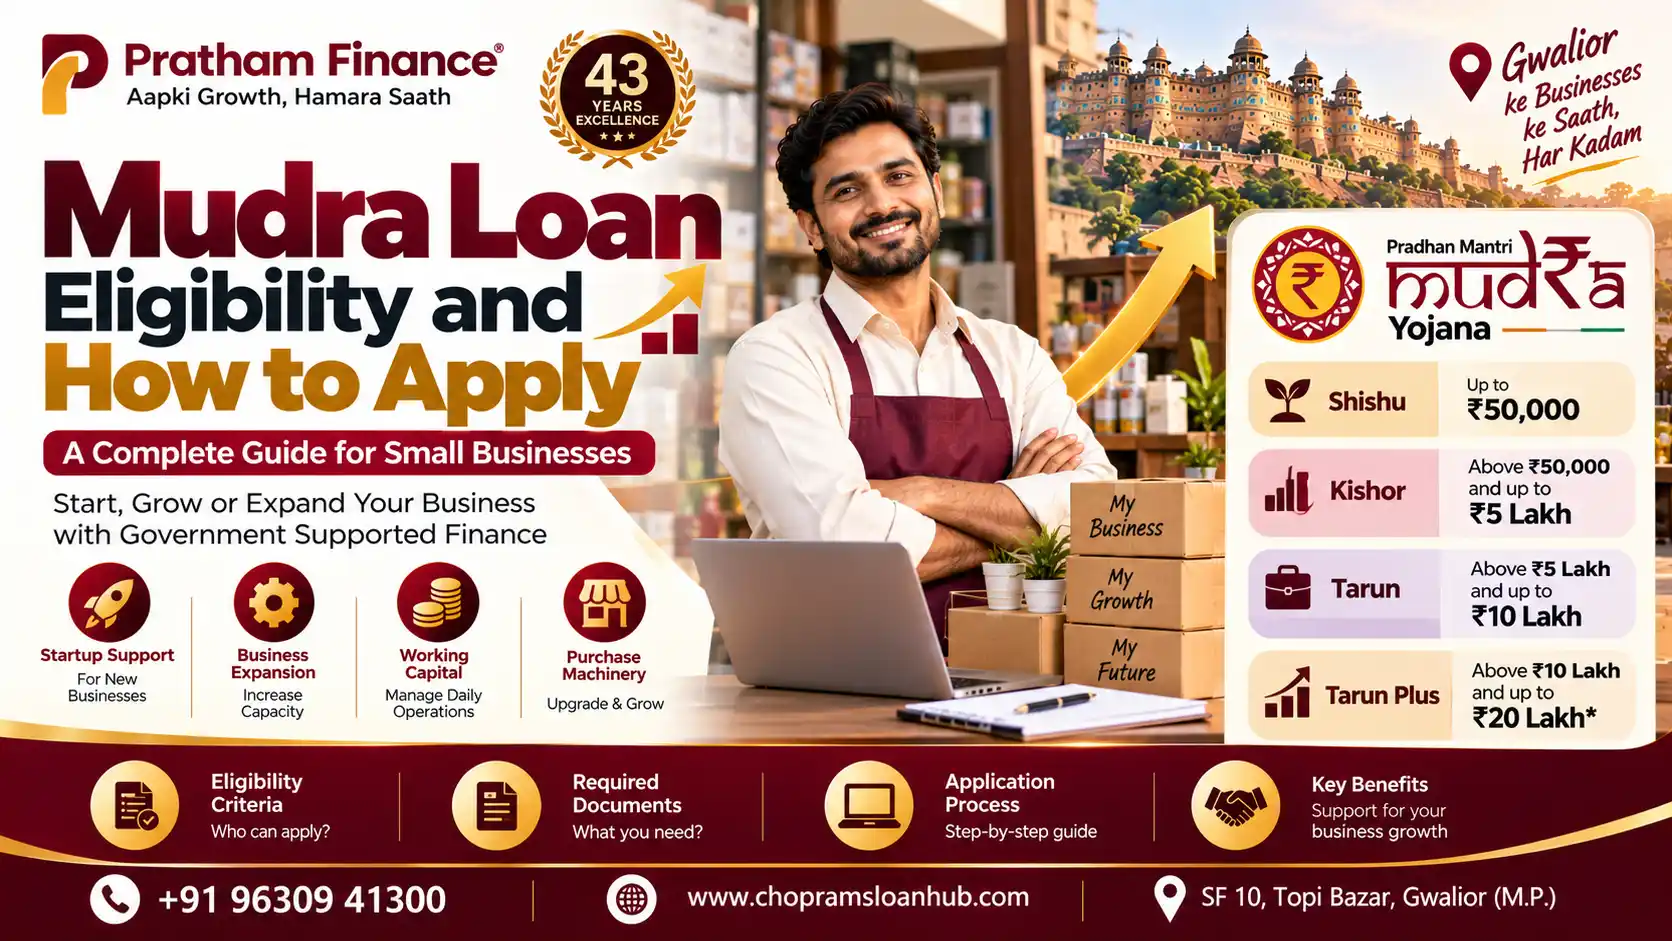
2. Pradhan Mantri MUDRA Yojana (PMMY)
PMMY supports eligible micro and small business activities through participating financial institutions.
Its loan categories include Shishu, Kishor, Tarun and Tarun Plus, subject to the applicable eligibility conditions. Tarun Plus is intended for eligible entrepreneurs who have successfully repaid a previous Tarun loan.
MUDRA financing may suit smaller funding requirements. Eligibility, limits and collateral conditions should be verified with the participating lender under current rules.
3. Stand-Up India and Other Applicable Programmes
Certain government programmes target specific groups of entrepreneurs or types of business activity. Their eligibility conditions, availability and terms can change.
Do not assume that every scheme is open to every applicant or that a scheme automatically guarantees collateral-free funding. Confirm the current status and requirements through official government sources or a participating lender.
Who Can Apply for a Collateral-Free Business Loan?
Eligibility differs between lenders. The following profiles may be considered, depending on the product:
- Proprietorship businesses.
- Partnership firms.
- Limited liability partnerships (LLPs).
- Private limited companies.
- Eligible traders and wholesalers.
- Manufacturing units.
- Service-based businesses.
- Eligible small and medium-sized enterprises.
- Established businesses seeking funds for expansion or working capital.
Some lenders also offer selected products to newer businesses, but businesses with a limited financial track record may face additional eligibility requirements.
Common Eligibility Factors
1. Business vintage: Some lenders require the business to have operated for a minimum period.
2. Turnover: The lender may review annual sales, transaction history and the stability of business income.
3. Credit score: A strong credit profile can improve the assessment, although the required score varies by lender and product.
4. Repayment capacity: The business should generate sufficient cash flow to meet the proposed instalments and existing obligations.
5. Financial documentation: Reliable bank statements, tax returns and accounting records can help establish financial credibility.
6. Business profile: The nature of the activity, industry risks and purpose of the loan may influence the decision.
There is no universal minimum turnover, credit score or business age that guarantees approval across all lenders.
Documents Required for a Collateral-Free Business Loan
Preparing accurate documentation can help reduce delays during the application process.
Commonly Requested Documents
Identity and address proof
- PAN card of the applicant or relevant business entity.
- Aadhaar or other accepted identity and address proof, as applicable.
- Photograph and KYC documents where required.
Business documents
- Udyam Registration Certificate, if applicable.
- GST registration and returns, where applicable.
- Business registration documents.
- Partnership deed or company incorporation documents, as applicable.
- Business address proof and relevant licences.
Financial documents
- Recent bank statements, commonly covering 6–12 months depending on the lender.
- Income-tax returns and financial statements for the requested period.
- Profit and loss statement and balance sheet, where applicable.
- Details of existing loans and repayment obligations.
- Sales records and cash-flow information.
Additional documents
- A brief business profile or expansion plan.
- Machinery quotations or supplier invoices, where relevant.
- Other information requested by the lender based on the application.
The exact checklist varies by lender, legal structure, loan amount and scheme. Submit documents only through verified channels and avoid sharing sensitive financial information with unverified intermediaries.
How to Get a Collateral-Free Business Loan: Step-by-Step Process
Step 1: Calculate Your Actual Funding Requirement
Determine how much money your business needs and why.
For example:
- Inventory purchase: ₹5 lakh.
- Machinery and equipment: ₹10 lakh.
- Business expansion: ₹15 lakh.
- Additional working capital: ₹8 lakh.
These are illustrative figures. Request an amount supported by your actual business needs rather than borrowing more than you can comfortably repay.
Step 2: Review Your Business Financials
Check your recent turnover, profit margins, cash flow, existing debt and repayment history.
If your business finances are disorganised, prepare updated accounts before applying. Clear financial records make it easier for a lender to assess the business.
Step 3: Check Your Credit Profile
Review your credit report for outstanding balances, overdue payments and reporting errors.
Where possible, clear overdue amounts, correct genuine errors and avoid making multiple unnecessary loan applications in a short period.
Step 4: Compare Suitable Financing Options
Explore eligible offers from banks, NBFCs and participating institutions. Compare more than the advertised interest rate.
Consider:
- Interest rate and whether it is fixed or floating.
- Annual percentage cost or other disclosed overall borrowing costs.
- Processing fees and other charges.
- Repayment tenure and instalment amount.
- Prepayment or foreclosure charges, where applicable.
- Personal guarantee and collateral conditions.
- Consequences of missed payments.
Step 5: Prepare and Submit Your Documents
Ensure that your application details match your PAN, bank records, tax filings and business documents.
Explain the purpose of the loan and provide supporting estimates or quotations when requested.
Step 6: Complete the Lender's Assessment
The lender may verify your identity, business operations, financial records, credit history and repayment capacity.
It may request additional information before deciding whether to approve the application.
Step 7: Review the Sanction Terms Before Accepting
Read the sanction letter and loan agreement carefully. Verify the sanctioned amount, interest rate, fees, tenure, repayment schedule, security conditions and default-related charges.
Accept the offer only if the terms are clear and the repayment commitment is manageable.
How Pratham Finance Can Help Business Owners in Gwalior
Finding an appropriate financing option can take time, particularly when you are comparing lenders, checking documentation and evaluating different loan structures.
Pratham Finance, Gwalior, can be approached for assistance in exploring business loan options, including potential collateral-free financing, subject to the services it currently provides and the eligibility criteria of the relevant lender.
Business owners can discuss their funding needs, business profile and available documents to understand which financing options may be worth considering.
Businesses That May Explore Financing
- Retail shops and wholesale traders.
- Small manufacturing units.
- Distributors and suppliers.
- Service-based businesses.
- Established MSMEs planning expansion.
- Businesses requiring additional working capital.
- Eligible enterprises purchasing machinery or increasing inventory.
Why Evaluate Your Options Before Applying?
A suitable loan structure can help a business fund growth without putting unnecessary pressure on monthly cash flow.
Before proceeding, confirm with Pratham Finance whether it assists with the relevant loan category, which lenders or schemes are available, what fees apply to its services, and whether the proposed product requires collateral or a personal guarantee.
Loan approval, interest rates, funding limits and disbursement timelines are determined by the relevant lender and are not guaranteed by a loan assistance provider.
7 Practical Tips to Improve Your Loan Approval Chances
1. Maintain a Healthy Credit History
Pay existing EMIs and credit card dues on time. Avoid taking on additional borrowing that your business cannot comfortably repay.
2. Keep Business and Personal Transactions Organised
Use appropriate business banking arrangements and maintain clear records of sales, expenses and major transactions.
3. File Tax Returns Accurately
Regular and consistent tax compliance can help lenders verify your business activity and financial position.
4. Maintain Updated Udyam and GST Records
Where applicable, ensure your business registrations and filings are accurate and current.
5. Prepare a Clear Funding Plan
Explain how the loan will be used and how the business expects to repay it. A machinery quotation, inventory estimate or expansion plan may help support your application.
6. Choose a Realistic Loan Amount
The amount requested should align with your business income, cash flow and repayment capacity.
7. Compare Offers Before Signing
A loan with a lower advertised interest rate may still have significant fees or restrictive terms. Compare the total cost and contractual conditions before making a decision.
Frequently Asked Questions (FAQs)
1. How can I get a collateral-free loan for my business?
Start by calculating your funding requirement, reviewing your credit profile, preparing financial documents and comparing eligible unsecured business loan products. Banks, NBFCs and qualifying government-backed credit guarantee arrangements may offer relevant options. Approval depends on the lender's assessment.
2. Can I get a business loan without property in Gwalior?
Yes, eligible businesses in Gwalior may be able to apply for business financing without pledging property. Availability depends on the lender, business financials, credit history and product conditions. Contact Pratham Finance to enquire about the options it currently assists with.
3. What is the maximum amount available under a collateral-free business loan?
There is no single maximum applicable to every collateral-free business loan. The amount depends on the product, lender, credit assessment and applicable guarantee scheme. Do not assume that a high-value loan will be available without security simply because an advertisement describes it as collateral-free.
4. Is a collateral-free business loan available for new businesses?
Some lenders offer financing to newer businesses, but eligibility may be more restrictive when the business has limited operating history or financial records. The applicant may need to provide additional evidence of business viability, income or repayment capacity.
5. Is a collateral-free business loan available under a government scheme?
Eligible businesses may be able to access financing supported by programmes such as CGTMSE or PMMY, subject to current scheme rules and participating lender requirements. These programmes are not universal guarantees of approval. Confirm the applicable conditions before applying.
6. Does Pratham Finance guarantee business loan approval?
No responsible loan assistance provider should be assumed to guarantee approval. If you approach Pratham Finance in Gwalior, confirm the services it provides and the relevant lender's eligibility requirements. The final decision rests with the lender, and the borrower should review all terms before accepting a loan.
Conclusion: Explore the Right Collateral-Free Business Loan for Your Business
A collateral-free business loan may be a useful financing option for eligible entrepreneurs who want to expand operations, increase inventory, purchase equipment or manage working capital without pledging traditional assets.
The best approach is to understand your funding requirement, organise your financial records, compare suitable lenders and select a repayment structure that your business can sustain.
If you are a business owner in Gwalior, contact Pratham Finance to enquire about available business loan assistance and potential collateral-free financing options. Discuss your business profile, documentation and funding needs before choosing a product.
Disclaimer: This article is for general educational and informational purposes only and does not constitute financial, investment, legal or tax advice. Loan availability, interest rates, fees, eligibility, collateral requirements and approval depend on the relevant lender and applicable rules. Government scheme terms may change. Verify all current conditions with official sources and the lending institution before applying.