MSME Business Loans
MSME Business Loan in India: Eligibility, Documents, Interest Rates & How to Apply
Learn how MSME business loans work in India, who can apply, which documents are required, and how to prepare a strong loan application for business growth.
MSME Business Loan in India: Eligibility, Documents, Interest Rates & How to Apply
Small and medium-sized businesses play an important role in India's economy. Whether you run a manufacturing unit, trading business, wholesale operation, service company or small enterprise, access to timely finance can help you manage daily expenses and plan future growth.
An MSME business loan can help eligible businesses arrange funds for working capital, machinery, inventory, business expansion and other approved business requirements. However, the right funding option depends on your business profile, financial records, repayment capacity and the lender's eligibility criteria.
In this guide, we explain how MSME business loans work, the documents you may need and the steps you can take before applying.
What Is an MSME Business Loan
An MSME business loan is financing intended to support eligible micro, small and medium enterprises. Depending on the lender and product, the funds may be used for operational expenses, purchasing equipment, increasing stock, expanding a facility or managing cash-flow requirements.
Businesses may consider different types of finance, including:
- Working Capital Finance: Helps manage short-term operational expenses and cash-flow gaps.
- Term Loan: May be used for machinery, equipment, infrastructure or expansion.
- Cash Credit or Overdraft: Provides access to funds within an approved limit, subject to the facility's terms.
- Machinery Finance: Helps eligible businesses acquire or upgrade equipment
- Business Expansion Finance: Supports eligible growth projects and capacity expansion.
The availability and suitability of each option depend on the lender's assessment and the business's requirements.
Who Can Apply for an MSME Business Loan?
Eligibility varies by lender and loan product. Common applicants may include:
- Manufacturers and industrial units
- Traders, distributors and wholesalers
- Service-sector businesses
- Proprietorships and partnership firms
- Limited liability partnerships and companies
- Eligible registered MSMEs seeking working capital or expansion finance
Lenders may assess business vintage, annual turnover, profitability, existing liabilities, banking transactions, credit history and repayment capacity.
Udyam registration may be relevant for MSME classification and certain schemes, but it does not automatically guarantee loan approval.
Documents Commonly Required for an MSME Loan
Prepare the documents relevant to your business structure and loan requirement. A lender may request:
- PAN and identity documents of the proprietor, partners or authorised directors.
- Business address proof and applicable registration documents.
- Udyam registration certificate, where applicable.
- GST registration and GST returns, where applicable.
- Bank statements for the period specified by the lender.
- Income tax returns and financial statements.
- Profit and loss account and balance sheet.
- Details of existing loans and repayment obligations.
- Estimated project cost and quotations for machinery or equipment, if applicable.
- Project report and projected cash flows for expansion proposals, where required.
The exact checklist can vary depending on the amount requested, the type of finance and the lender's policy.
How Much Business Loan Can You Get?
There is no single loan amount available to every MSME. The amount offered depends on factors such as turnover, cash flow, profitability, banking activity, existing debt, security arrangements and the purpose of the loan.
For example, a business with regular sales and strong repayment capacity may be assessed differently from a business with irregular cash flow or significant existing liabilities.
If you require a substantial amount for an industrial project or expansion, prepare a clear proposal showing:
- Current business performance
- Purpose and break-up of the funding requirement
- Existing borrowing and repayment commitments
- Expected increase in revenue or production
- Projected cash flow and repayment plan
Do not assume that a particular percentage of turnover will automatically be sanctioned. The final limit is subject to assessment and lender approval.
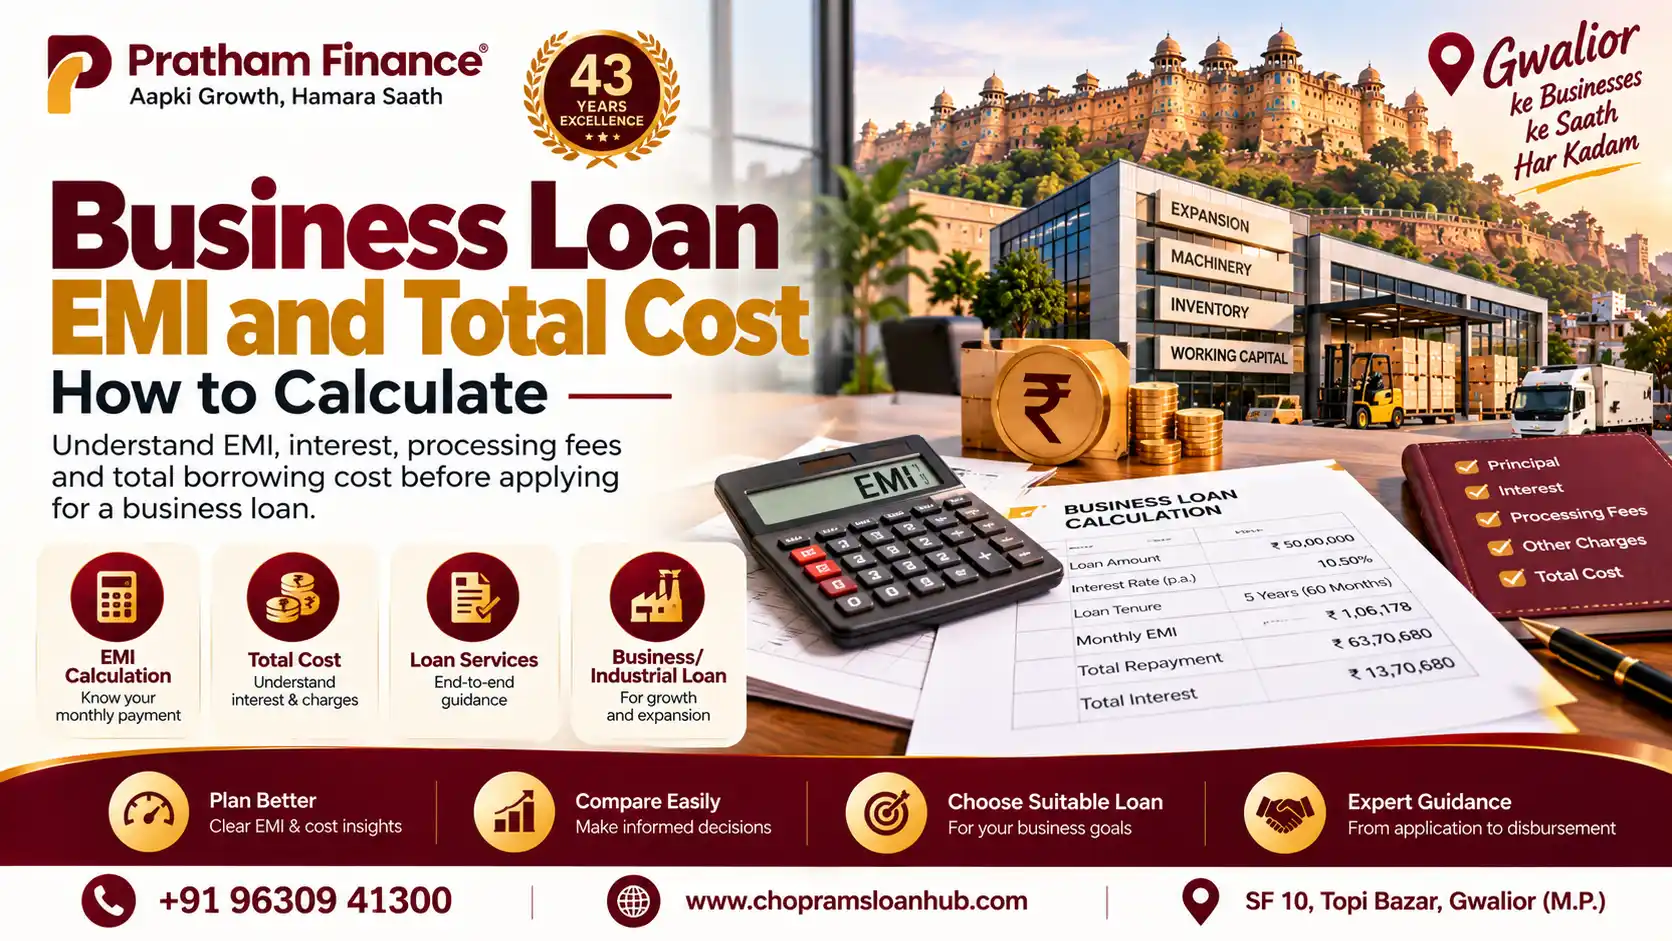
What Is the Interest Rate on an MSME Business Loan?
Interest rates vary across lenders and products. The applicable rate may depend on the borrower's credit profile, financial performance, loan amount, tenure, security and overall risk assessment.
Before accepting a loan offer, compare more than the advertised interest rate. Check:
- Processing fees and other charges
- Whether the rate is fixed or floating
- Repayment schedule and loan tenure
- Prepayment or foreclosure charges, if applicable
- Collateral and guarantee requirements
- The total repayment amount
Ask the lender for a written quotation and understand all terms before signing the agreement.
Is Collateral Required for an MSME Business Loan?
Not every business loan has the same security requirements. Some facilities may be available without traditional property collateral, while others may require security, a guarantee or a charge over business assets.
Eligible borrowers may also explore applicable credit guarantee schemes, subject to the scheme's rules and the lender's participation.
Machinery, inventory or receivables may form part of a financing arrangement where the lender permits it. Their acceptance does not mean that every loan can be approved without property security.
Always confirm the security conditions for your specific loan proposal.
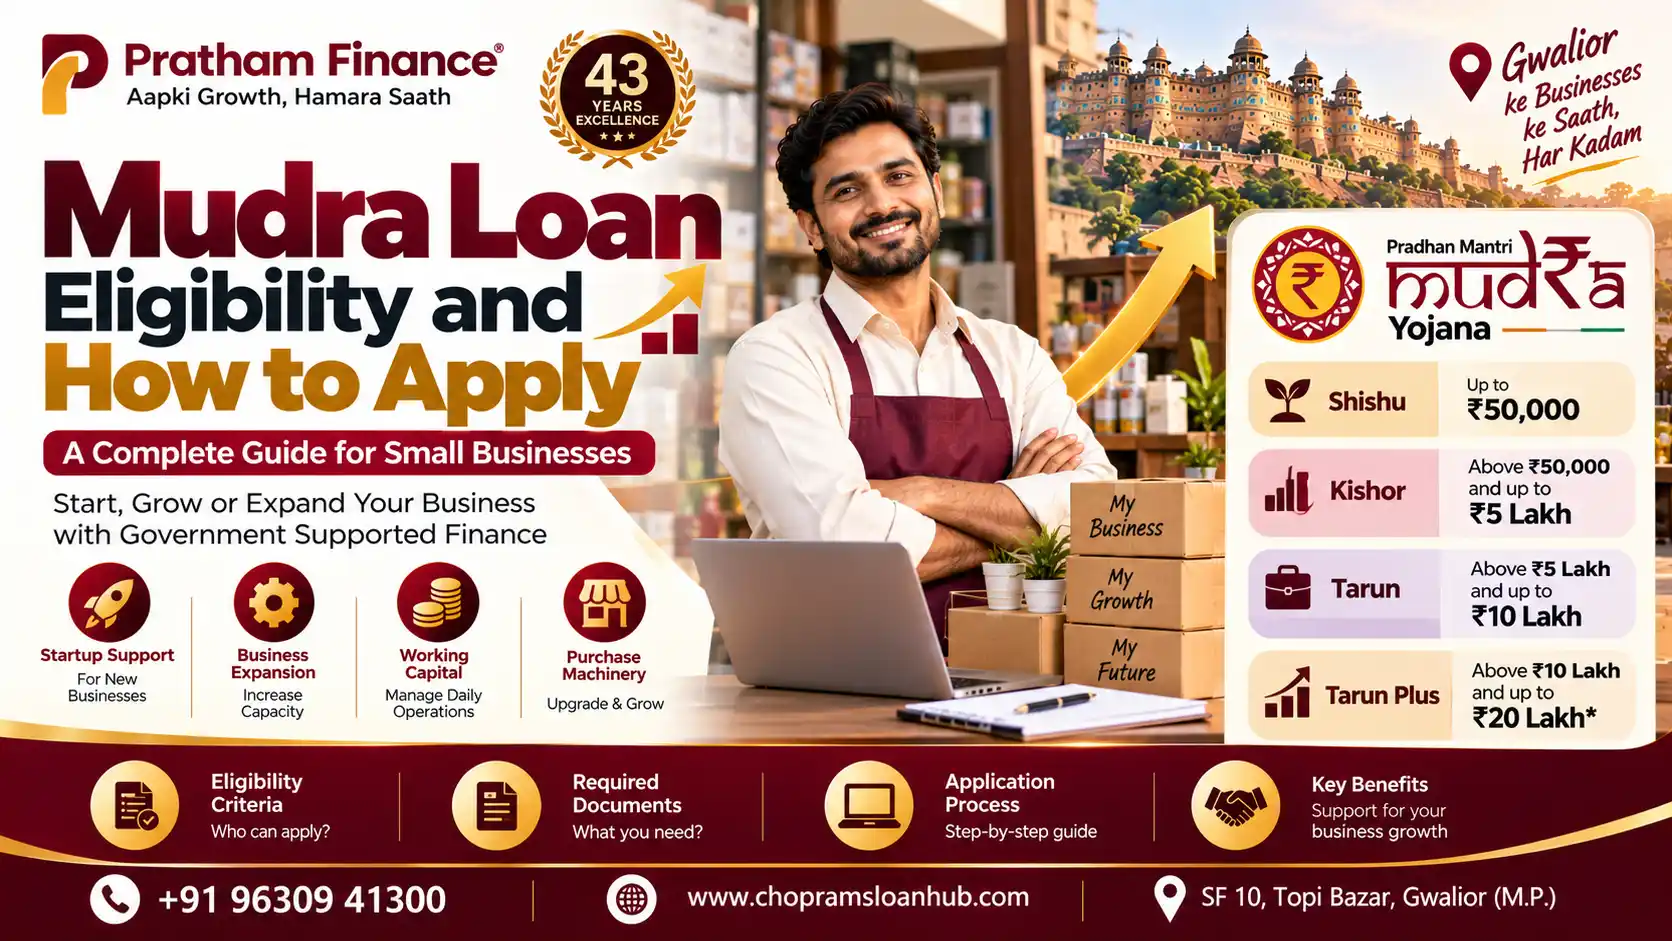
How to Apply for an MSME Business Loan
Follow these steps to prepare a stronger application:
Step 1: Define the requirement
Calculate how much funding you need and whether it is for working capital, machinery, inventory or expansion.
Step 2: Organise your financial records
Keep your bank statements, tax returns, financial statements and applicable GST records ready.
Step 3: Review existing liabilities
Prepare a list of current loans, outstanding balances and monthly repayment commitments.
Step 4: Prepare a business proposal
For a larger loan or expansion project, explain the purpose of the funds, project cost, expected business impact and repayment plan.
Step 5: Compare suitable funding options
Review the eligibility criteria, interest rate, fees, collateral requirements and repayment terms of available lenders.
Step 6: Submit your application
Provide accurate information and respond to document requests. Approval, the final sanctioned amount and disbursement depend on the lender's assessment.
Common Mistakes to Avoid
Avoid these mistakes when applying for business finance:
Applying without calculating the actual funding requirement
- Providing inconsistent turnover or financial figures
- Ignoring existing loan obligations
- Accepting an offer without reviewing additional charges
- Assuming that registration alone guarantees approval
- Paying unverified agents who promise guaranteed loan sanctions
Work only with verifiable lenders or authorised financial intermediaries, and review all documentation carefully.
How Chopra MSME Loan Hub Can Help
Chopra MSME Loan Hub can help business owners understand potential funding routes and prepare the information needed for a loan enquiry. Depending on the services actually offered, assistance may include understanding document requirements, organising financial information and exploring suitable funding options.
If you are planning business expansion, machinery purchases or working capital arrangements, begin by assessing your requirement and preparing your latest financial records.
Ready to discuss your business funding requirement?
Contact Chopra MSME Loan Hub through the contact details published on this website. Share your business type, approximate funding requirement and purpose of finance to begin an initial discussion.
Frequently Asked Questions
1. Can a small business apply for an MSME loan?
Eligible small businesses may apply, subject to the lender's requirements, financial assessment and applicable documentation.
2. Is Udyam registration enough to get a loan?
No. Udyam registration may help establish MSME classification, but it does not guarantee loan approval.
3. Can I apply for a loan for business expansion?
Depending on the lender and product, eligible businesses may seek finance for expansion, machinery, infrastructure or working capital.
4. Can an MSME loan be available without property collateral?
Some products or eligible guarantee-backed facilities may not require traditional property collateral. Conditions vary, and approval is not guaranteed.
5. How can I improve my chances of approval?
Maintain accurate financial records, disclose existing borrowing, explain the purpose of funding and demonstrate a realistic repayment plan.
Final Thoughts
Choosing an MSME business loan requires careful planning. Understand your funding requirement, organise your documents and compare the complete terms of available finance before making a decision.
A well-prepared application can make the assessment process clearer, but the final decision remains with the lender. Always verify the latest eligibility conditions, charges and loan terms before proceeding.